Wallester White Label
Wallester White Label provides branded accounts, cards, and payments through a mobile app, back-office portal, API, and regulated infrastructure.
What Wallester White Label is
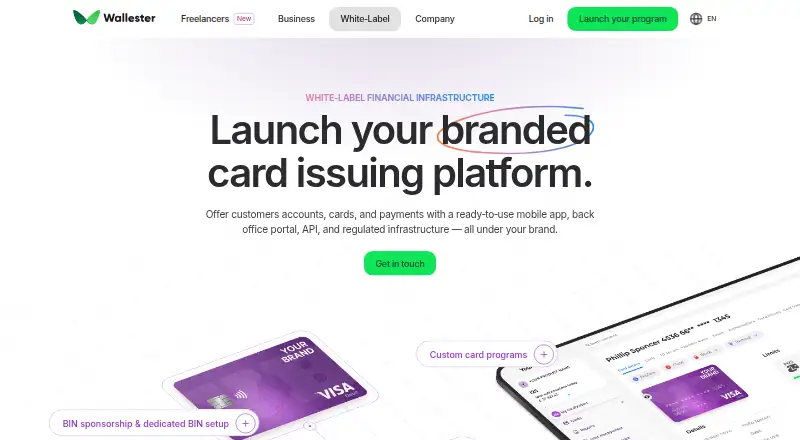
Wallester White Label provides branded accounts, cards, and payments through a mobile app, back-office portal, API, and regulated infrastructure. Businesses can configure debit, prepaid, or credit card programs for consumer, business, or corporate use. The portal lets teams manage users, cards, balances, limits, spending rules, approval flows, and program activity. Accounts and cards support EUR, GBP, PLN, SEK, NOK, DKK, CZK, HUF, RON, and USD, alongside global payments. A REST API connects card programs, controls, and payment workflows. The branded app supports Apple Pay and Google Pay using tokenized credentials. Programs can launch under Wallester’s issuer and scheme framework, with dedicated BIN setup available when needed. The platform includes KYC/KYB, AML, fraud monitoring, and payment processing. Wallester identifies itself as a Visa Principal Member and an Authorized Payment Institution licensed by Estonia’s Finantsinspektsioon, and states that it is PCI DSS Level 1 certified for payment data. The service is presented for the EEA and UK. Monthly plans are 2495.00 EUR for non-financial institutions, 3995.00 EUR for financial institutions, and 5995.00 EUR for VASP financial institutions.
Good
- Supports debit, prepaid, and credit card programs.
- Portal controls include balances, spending rules, and approvals.
- Accounts and cards support 10 listed currencies.
- Branded app supports Apple Pay and Google Pay.
- Includes KYC/KYB, AML, and fraud monitoring.
Watch out
- Plan pricing differs by institution type.
- The described coverage is the EEA and UK.
Who it suits
Wallester White Label is presented for regulated and non-regulated businesses, including banks, lenders, fintech companies, marketplaces, employers, and digital asset platforms. It suits organizations seeking branded card programs with account and payment controls.
Verdict
Wallester White Label combines branded card and account programs with portal controls, API connectivity, and compliance features. The monthly plans are priced by institution type, so choose the applicable category when evaluating the cost.
Plans and prices
From Wallester White Label's own pricing page, checked 5 Oct 2026.
| Plan | Price | What it gives you |
|---|---|---|
| White-Label for non-financial institutions | €2,495 a month | No setup or hidden fees stated · €2,495 / month |
| White-Label for financial institutions | €3,995 a month | No setup or hidden fees stated · €3,995 / month |
| White-Label for VASP financial institutions | €5,995 a month | No setup or hidden fees stated · €5,995 / month |
The facts
Each one read from Wallester White Label's own pages, with the date it was checked.
What it does
- Accounts and currencies
- The platform supports accounts and cards in EUR, GBP, PLN, SEK, NOK, DKK, CZK, HUF, RON, and USD, plus global payments.checked 5 Oct 2026
- API
- Wallester offers an in-house REST API for connecting cards, program controls, and payment workflows.checked 5 Oct 2026
- Back-office controls
- The portal lets teams manage cards, users, balances, limits, spending rules, approval flows, and program activity.checked 5 Oct 2026
- BIN sponsorship
- Programs can launch under Wallester’s issuer and scheme framework, with dedicated BIN setup available where needed.checked 5 Oct 2026
- Card programs
- Businesses can configure branded debit, prepaid, or credit card programs for consumer, business, and corporate use cases.checked 5 Oct 2026
- Compliance
- The platform includes KYC/KYB, AML, fraud monitoring, and payment processing, and identifies Wallester as a Visa Principal Member and an Authorized Payment Institution licensed by Estonia’s Finantsinspektsioon.checked 5 Oct 2026
- Coverage
- The White-Label page describes multi-currency accounts, cards, and payments for the EEA and UK.checked 5 Oct 2026
- Launch timing
- Wallester says a first virtual card can be available in 30 days and physical cards can follow in up to two months.checked 5 Oct 2026
- Mobile wallets
- The branded mobile app supports Apple Pay and Google Pay, using tokenized credentials for wallet payments.checked 5 Oct 2026
- Product
- Wallester White-Label provides branded accounts, cards, and payments through a mobile app, back-office portal, API, and regulated infrastructure.checked 5 Oct 2026
- Security
- Wallester states that it is PCI DSS Level 1 certified for handling payment data.checked 5 Oct 2026
- Target customers
- The service is presented for regulated and non-regulated businesses, including banks, lenders, fintech companies, marketplaces, employers, and digital asset platforms.checked 5 Oct 2026
The company
- Company
- Wallester’s about page describes it as a fintech company providing a platform for digital payments and card issuance, with a Tallinn office; a Wallester article says it was founded in Tallinn in 2016.checked 5 Oct 2026
- Founded
- 2016checked 28 Sep 2026
- Headquarters
- Tallinn, Estoniachecked 28 Sep 2026
The full review of Wallester White Label
Wallester White Label is a configurable infrastructure service for organisations launching branded accounts, cards and payment products. It suits banks, fintechs, lenders, marketplaces, employers and digital-asset businesses that can manage programme and compliance responsibilities. The central trade-off is clear: broad issuing and control capabilities come with substantial recurring fees and a business-oriented implementation process.
Overview
The platform combines a branded mobile app, back-office portal, REST API and regulated payment infrastructure. Operators can create debit, prepaid or credit programmes for consumer, business or corporate customers, while keeping control of the user experience and programme rules. Wallester supplies payment processing alongside KYC/KYB, AML and fraud-monitoring functions.
Wallester identifies itself as a Visa Principal Member and an Authorized Payment Institution licensed by Estonia’s Finantsinspektsioon, and states that it is PCI DSS Level 1 certified for payment-data handling. Those capabilities support a serious operating model, although each business remains responsible for its own regulatory decisions and customer obligations. Coverage targets the EEA and UK, with multi-currency accounts and cards in EUR, GBP, PLN, SEK, NOK, DKK, CZK, HUF, RON and USD, plus global payments.
A first virtual card may be available in 30 days, while physical cards can follow in up to two months. That timeline is useful for a planned launch but will not satisfy a company seeking an immediate, self-serve card product.
Key features
- Configurable card programmes: Debit, prepaid and credit cards can be branded for consumer, business or corporate use. Multi-programme support makes the service suitable for organisations serving distinct customer groups.
- Operational controls: The portal manages cards, users, balances, limits, spending rules, approval flows and programme activity. This is valuable for finance teams that need central governance; it is more infrastructure than a lightweight expense app requires.
- API connectivity: The in-house REST API connects issuing, programme controls and payment workflows to existing products. API access supports embedded experiences, but implementation still demands engineering resources.
- Wallet-ready mobile app: Branded apps support Apple Pay and Google Pay through tokenized credentials, giving cardholders mainstream mobile-wallet payments.
- Issuer and compliance foundation: Dedicated BIN setup is available where needed, while KYC/KYB, AML, fraud monitoring and processing are included in the platform’s regulated infrastructure.
- Funding and card breadth: Virtual and physical cards, funding and balances, spend controls and an issuing API are all supported.
Pricing
Pricing is monthly and depends on the institution category. White-Label for non-financial institutions costs €2,495 a month, billed at €2,495 per month, with no setup or hidden fees stated. It is the entry point for employers, marketplaces and other non-financial operators, but remains a significant fixed cost before card volume or revenue is considered.
White-Label for financial institutions costs €3,995 a month, billed at €3,995 per month, with no setup or hidden fees stated. Banks, lenders and fintechs should choose this tier when their organisation falls into the financial-institution category; the higher fee reflects the intended operating context rather than a small-team starter plan.
White-Label for VASP financial institutions costs €5,995 a month, billed at €5,995 per month, with no setup or hidden fees stated. It is aimed at virtual-asset-service-provider financial institutions and is the most expensive commitment. No seat, card-volume, trial or renewal limits are stated, so prospective buyers should obtain those commercial terms before budgeting.
Platforms
Wallester supports Android, iOS, web and API access. The combination covers branded customer apps, browser-based administration and system-to-system integration. The API is especially important for businesses embedding issuing and payments into another product, while the mobile and web surfaces support cardholder and operations workflows.
Who it's for
This is a strong fit for regulated or regulation-aware organisations that need their own card proposition across the EEA or UK and can absorb a multi-thousand-euro monthly platform cost. Banks, fintech companies, lenders, marketplaces, employers and digital-asset platforms are the clearest candidates. A small company validating demand, or one needing only simple employee cards, is likely better served by a lower-commitment product.
Pros and cons
Pros
- One service covers branded accounts, virtual and physical cards, payments, controls and balances.
- Multi-currency support spans ten listed currencies and includes global payments.
- API, portal and mobile-wallet support allow both embedded and branded customer experiences.
- KYC/KYB, AML, fraud monitoring, BIN sponsorship and stated Visa and Estonian payment-institution credentials support a credible issuing foundation.
Cons
- Monthly prices from 2,495.00 EUR make it unsuitable for experimental or low-volume programmes.
- Physical-card delivery may take up to two months after the initial virtual-card launch.
- Commercial limits such as seats, quotas, trial availability and renewal terms require clarification before purchase.
Alternatives
Choose Extend instead if you need a freemium expense-card product: its free Starter plan allows up to five users, ten guests and 100 virtual cards per month, but it is not a like-for-like white-label issuing platform. Paynetics Card Issuing is worth considering for customisable Visa or Mastercard programmes with physical and virtual cards and custom pricing.
Visa DPS Forward fits teams wanting an API-led route with a free sandbox and production fees handled through contact. Conferma Pay is another demo-led platform with Android, iOS, web and API access. Interlace, Marqeta and Thredd are paid API/web alternatives for organisations comparing issuing infrastructure. Mastercard Decision Intelligence is a paid web service focused on decision intelligence rather than a full branded card-and-account stack.
For a wider comparison, browse Card Issuing Platforms.
Verdict
Wallester White Label is best for an established organisation that wants branded, multi-currency card and account programmes with API control, wallet support and built-in compliance infrastructure. Its main reason to choose it is the breadth of issuing and operational capabilities in one platform. Look elsewhere if the programme is small, unproven or needs transparent low-cost pricing, because the recurring commitment and implementation timeline are substantial.
Alternatives to Wallester White Label
- 1
Extend
Free planAndroidiOSWebAPI7.9Free plan - 2
Paynetics Card Issuing
AndroidiOSWebAPI6.5 - 3
Visa DPS Forward
Free planAPI6.4Free plan - 4
Conferma Pay
AndroidiOSWebAPI6.3 - 56.1
- 6
Stripe Issuing
WebAPI5.9$0.10 one-time