NymCard
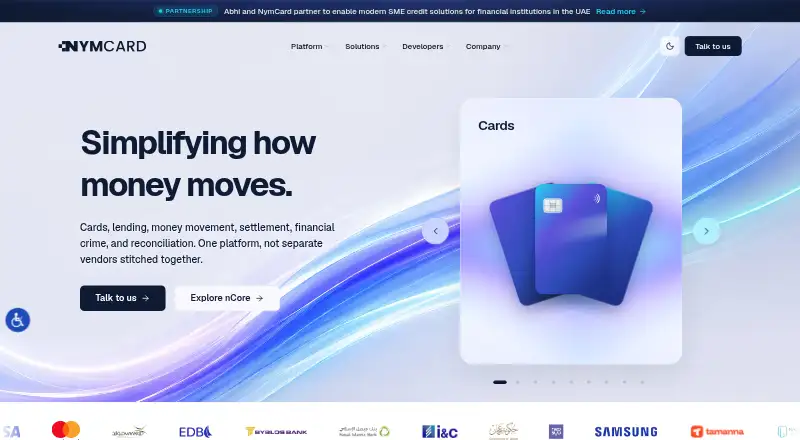
NymCard’s nCore is a payments platform for banks, fintechs, and businesses building financial products.
What NymCard is
NymCard’s nCore is a payments platform for banks, fintechs, and businesses building financial products. It brings together card issuing, money movement, settlement, reconciliation, lending infrastructure, and financial-crime capabilities. Organizations can issue debit, credit, and prepaid cards as physical, virtual, or tokenized cards, and configure spending limits, billing cycles, repayment, and installments through APIs. Payment functions include domestic and cross-border payments, foreign exchange, and remittances. Wallet capabilities cover top-ups, transfers, peer-to-peer and merchant payments, bill payments, and cash in and out. Its financial-crime tools include identity verification, fraud monitoring, risk management, and AML and sanctions screening. NymCard describes nCore as API-driven, with REST APIs, webhooks, implementation guides, and developer resources. It can connect to existing core banking platforms without replacing them and can run in public cloud, hybrid, on-soil, or fully on-premise deployments. Lending tools support credit decisioning, origination, and servicing, but NymCard does not fund loans. Pricing is available on request.
Good
- Supports physical, virtual, and tokenized cards.
- Includes domestic and cross-border payment capabilities.
- Offers cloud, hybrid, on-soil, and on-premise deployment.
- Lists PCI DSS Level 1 and SOC 2 Type II certification.
Watch out
- Pricing is available only on request.
- NymCard does not fund loans.
- Supported regions are limited to eight listed countries.
Who it suits
NymCard suits banks, fintechs, and businesses building card, payment, or other financial products. Its deployment choices and API integration may suit organizations with specific hosting or core-banking needs.
Verdict
NymCard brings card, payment, wallet, compliance, and lending infrastructure into one platform. Buyers should confirm regional availability and pricing, and note that lending funding is not included.
Plans and prices
From NymCard's own pricing page, checked 9 Oct 2026.
| Plan | Price | What it gives you |
|---|---|---|
| nCore | Priced on request | Pricing not published; talk to NymCard |
The facts
Each one read from NymCard's own pages, with the date it was checked.
What it does
- API integration
- NymCard describes nCore as an API-driven platform and provides REST APIs for building and managing card programs.checked 9 Oct 2026
- Audience
- NymCard describes its platform as serving banks, fintechs, and businesses building financial products.checked 9 Oct 2026
- Card controls
- Card programs can configure spending limits, billing cycles, repayment, and installments through the API.checked 9 Oct 2026
- Card issuing
- The platform supports debit, credit, prepaid, and wallet products.checked 9 Oct 2026
- Cards
- The platform supports debit, credit, and prepaid cards issued as physical, virtual, or tokenized cards.checked 9 Oct 2026
- Customer view
- The platform uses a shared 360-degree customer view and a real-time data core across its capabilities.checked 9 Oct 2026
- Data residency
- NymCard describes on-soil hosting as hosted within the customer's country to meet in-country data-residency requirements.checked 9 Oct 2026
- Deployment
- nCore can run in public cloud, hybrid, on-soil, or fully on-premise deployments.checked 9 Oct 2026
- Developer tools
- NymCard documentation describes API integration resources and directs developers to its sandbox, API catalog, and internal analytics tools.checked 9 Oct 2026
- Financial crime
- Its financial crime capabilities include identity verification, fraud monitoring, risk management, AML and sanctions screening, and issuer-side 3D Secure.checked 9 Oct 2026
- Integration
- NymCard says customers can select the layers they need through one integration, and offers APIs, webhooks, implementation guides, and developer tooling.checked 9 Oct 2026
- Integrations
- NymCard says its platform connects to existing core banking platforms without requiring their replacement.checked 9 Oct 2026
- Intended customers
- NymCard identifies banks, fintechs, and businesses as customers for its payments infrastructure.checked 9 Oct 2026
- Lending limit
- NymCard provides lending infrastructure for credit decisioning, origination, and servicing, but does not fund loans.checked 9 Oct 2026
- Lending limitation
- NymCard provides lending infrastructure for credit decisioning, origination, and servicing, but says it does not fund loans.checked 9 Oct 2026
- Networks
- NymCard identifies Visa and Mastercard as principal-member networks.checked 9 Oct 2026
- Payments
- Money movement capabilities include domestic rails, cross-border payments, foreign exchange, and remittances.checked 9 Oct 2026
- Product
- nCore combines card issuing, money movement, settlement, reconciliation, lending, and financial crime capabilities on one payments platform.checked 9 Oct 2026
- Public product pricing
- The platform pages direct prospective customers to talk to NymCard and do not state a platform subscription price.checked 9 Oct 2026
- Security
- NymCard states that nCore is certified for PCI DSS Level 1, PCI SSF, SOC 2 Type II, and ISO 27001.checked 9 Oct 2026
- Support
- The site directs prospective customers to contact its team and directs developers to documentation.checked 9 Oct 2026
The company
- Company
- NymCard says it was founded in 2018 by Omar Onsi.checked 9 Oct 2026
- Company scale
- NymCard's About page states it has more than 150 people and seven offices.checked 9 Oct 2026
- Founded
- 2018checked 28 Sep 2026
The full review of NymCard
NymCard is financial infrastructure for organizations building payment and banking products, rather than a consumer app. It is a strong fit for banks, fintechs, and businesses that want card, wallet, and compliance capabilities connected through APIs. The broad toolkit is compelling, but teams should account for implementation demands, regional coverage, and the fact that NymCard does not fund loans.
Overview
Its nCore platform combines card issuing with money movement, settlement, reconciliation, lending infrastructure, and financial-crime controls. Customers can select the layers they need and connect them to an existing core banking platform, avoiding a forced replacement. That makes NymCard a flexible foundation for a financial product, not a turnkey service for companies looking to launch without integration work.
Supported markets are the United Arab Emirates, Saudi Arabia, Qatar, Lebanon, Pakistan, Egypt, Iraq, and Sudan. NymCard identifies Visa and Mastercard as principal-member networks. Organizations outside those regions should confirm fit before investing in a program design.
Key features
Card issuing and controls. NymCard supports debit, credit, prepaid, and wallet products, with physical, virtual, or tokenized cards. APIs allow programs to set spending limits, billing cycles, repayment, and installments. This is useful for products with distinct card and credit rules, but those controls are building blocks: customers still need to define and implement their program.
Payments and wallets. The platform supports domestic rails, cross-border payments, foreign exchange, remittances, and wallet activity including top-ups, peer-to-peer and merchant payments, bill payments, transfers, and cash in and out. Bringing these capabilities together can reduce the number of systems a product team must coordinate; the breadth is most valuable when a product needs several of them, rather than a single isolated payment function.
Compliance and risk. Identity verification, fraud monitoring, risk management, AML and sanctions screening, and issuer-side 3D Secure address important parts of operating payment products. These tools suit organizations that need compliance capabilities within their infrastructure stack, though the platform does not remove the customer's responsibility to design its controls and operations.
Integration and deployment. NymCard describes nCore as API-driven, with REST APIs, webhooks, implementation guides, a sandbox, API catalog, and internal analytics tools. A shared customer view and real-time data core connect the platform's capabilities. Deployment options include public cloud, hybrid, on-soil hosting within the customer's country, and fully on-premise operation. This range is valuable for teams with specific infrastructure or data-residency needs, but prospective customers should assess the integration and deployment work against their own requirements.
Lending and security. NymCard provides lending infrastructure for credit decisioning, origination, and servicing, but does not fund loans. It can support the operating side of a credit product, not supply the capital. NymCard states that nCore is certified for PCI DSS Level 1, PCI SSF, SOC 2 Type II, and ISO 27001.
Pricing
NymCard is a paid platform with custom pricing; the subscription price is not published, and prospective customers are directed to contact the company. There are no published plan prices or self-serve tiers to compare. This makes it difficult for early-stage teams to assess cost before a sales conversation, so buyers should establish pricing and program requirements early.
The nCore plan has custom pricing. Its scope can be configured around the layers a customer needs, rather than a published fixed package. The value of that flexibility depends on the proposed scope and commercial terms, which organizations should confirm directly.
Platforms
NymCard supports Android, iOS, web, APIs, and self-hosted deployment. The combination addresses both product-facing mobile and web experiences and infrastructure integration, while self-hosted options are relevant to organizations with deployment constraints.
Who it's for
NymCard is aimed at banks, fintechs, and businesses building financial products that need several capabilities—such as cards, wallets, payments, and financial-crime controls—under one integration. It is particularly relevant to teams that want to retain an existing core banking platform or need cloud, hybrid, in-country, or on-premise deployment choices.
It is a weaker fit for companies seeking a simple off-the-shelf card product, a consumer banking app, or a lending provider that supplies loan capital. Its supported regions also make geographic fit an important qualification.
Pros and cons
- Pros: Broad product coverage. Cards, payment flows, wallets, settlement, reconciliation, lending operations, and financial-crime tools sit within one platform, which can suit teams assembling a multi-part financial product.
- Pros: Flexible integration and deployment. APIs and connections to existing cores, alongside cloud, hybrid, on-soil, and on-premise options, give organizations room to match the platform to their architecture.
- Pros: Multiple card types and controls. Physical, virtual, and tokenized cards plus configurable limits and repayment rules support varied program designs.
- Cons: Loan funding is outside the platform. Customers must arrange capital themselves even when using NymCard's decisioning, origination, and servicing infrastructure.
- Cons: Custom pricing requires a sales process. With no public subscription price or fixed self-serve tier, smaller teams cannot readily compare costs before engaging.
- Cons: Regional coverage is bounded. The supported markets are a defined set of eight countries, so organizations targeting other regions need to verify availability.
Alternatives
For a broader directory of providers, see Banking-as-a-Service Platforms.
- Railsr may suit teams that want to begin with a free, two-month live sandbox API, subject to account, value, and transaction restrictions, before considering its launch plan.
- Swan Cards is worth considering when a free sandbox with unlimited users and fake accounts, cards, and payments is the priority; its on-demand plan is listed at 2990.
- Stripe Treasury may fit teams seeking an API-based treasury option with no minimums or monthly fees, included ACH funding, and $2.00 wire funding.
- Unit is another paid API platform to compare when card program pricing, shipping, and order minimums need to be assessed against a specific design.
- Paynetics Card Issuing is an option to compare for customizable physical or virtual Visa and Mastercard programs.
- Treezor is another paid platform to consider.
- Vodeno Cloud Platform is another paid platform to consider.
- Mbanq Cloud may suit buyers looking for a pay-as-you-grow cloud platform with IT infrastructure, support, and operational costs included.
Verdict
NymCard is best for banks, fintechs, and businesses in its supported markets that need a configurable mix of card issuing, payments, wallets, and compliance infrastructure without replacing their existing core. Its main advantage is the breadth of capabilities and deployment choices under one API-driven platform. Look elsewhere if you need loan funding, a public price to budget against, or a region outside its supported footprint.
Alternatives to NymCard
- 1
Stripe Treasury
Free planAndroidiOSWebAPI7.9$0.50 one-time - 2
Swan Cards
Free planAndroidiOSWebAPI7.9From €900 a month - 3

Modulr
AndroidiOSWebAPI7.2From £16.25 a month - 4
Mbanq Cloud
AndroidiOSWebAPI6.9 - 5
Railsr
Free planWebAPI6.8Free plan - 6
Rapyd
AndroidiOSWebAPI6.8From $99 a month