Lokta
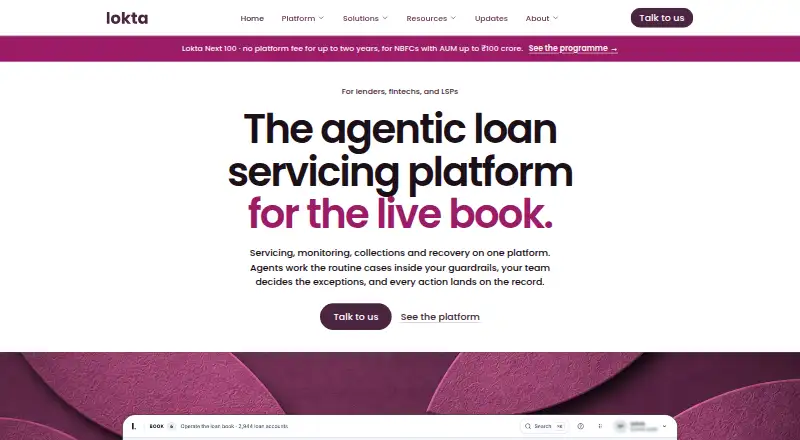
Lokta is an agentic loan servicing platform for managing loans after approval, including servicing, monitoring, collections, and recovery.
What Lokta is
Lokta is an agentic loan servicing platform for managing loans after approval, including servicing, monitoring, collections, and recovery. It supports books covering personal, consumer durable and BNPL, vehicle and EV, home, loan-against-property, business/MSME, and supply-chain or invoice finance. Its agents propose actions, while a deterministic core checks policies and approvals before updates reach the ledger. Connections include NACH and UPI rails, payment aggregators, core banking and escrow, credit bureaus, co-lending partners, collection agencies, and WhatsApp channels. Lokta can run on AWS, Microsoft Azure, Google Cloud, on-premises, or within a customer's virtual private cloud. Stated controls include role-based access, maker-checker workflows, audit trails, tenant-separated databases, and field-level PII encryption. Loan origination, underwriting, credit decisioning, and origination-time pricing are outside its scope. The Next 100 programme offers eligible NBFCs a zero platform fee for 24 months, but migration costs ₹1 lakh one-time plus applicable taxes and bank integration costs ₹50,000 plus applicable taxes. After the free term, the listed charge is ₹1,000 per crore monthly on AUM, plus applicable taxes; AI usage is metered separately.
Good
- Covers several consumer, commercial, and supply-chain loan types.
- Agents propose actions subject to policy and approval checks.
- Can be deployed in cloud, on-premises, or a customer VPC.
- Supports NACH and UPI payment rails.
- Tenants can pin deployments to a region.
Watch out
- Loan origination and underwriting are out of scope.
- Next 100 migration costs ₹1 lakh plus applicable taxes.
- Bank integration costs ₹50,000 plus applicable taxes.
- AI usage is metered separately after the free term.
Who it suits
Lokta is for banks, NBFCs, fintech lenders, and lending service providers managing loans after approval. Its supported loan books span consumer, vehicle, property, business, and supply-chain finance.
Verdict
Lokta is focused on post-approval loan servicing rather than origination or credit decisions. Eligible NBFCs should weigh the programme's free platform period against migration, integration, and later usage charges.
Plans and prices
From Lokta's own pricing page, checked 30 Sep 2026.
| Plan | Price | What it gives you |
|---|---|---|
| Lokta Next 100 | Free | NBFCs with AUM up to ₹100 crore at enrolment · excludes pure-play microfinance NBFCs · migration ₹1 lakh one-time plus applicable taxes · bank integration ₹50,000 plus applicable taxes · ₹0 platform fee for 24 months |
| Starter (Lokta Next 100) | Free | Assets up to ₹100 crore/about USD 10 million · migration ₹1 lakh one-time · bank integration ₹50,000 one-time · two new lenders per month · excludes pure-play microfinance NBFCs · ₹0 / USD 0 platform fee for 24 months |
| Lokta Next 100 after free term | ₹1 a month | Begins after 24 months or when average monthly AUM exceeds ₹100 crore for two consecutive months · AI usage metered separately · 1 bps per month on AUM (₹1,000 per crore), plus applicable taxes |
| Scale-up | $100 a month | Assets above Starter ceiling · implementation USD 5,000–10,000 one-time · standard hosted deployment · metered AI billed separately · taxes extra · USD 100 per USD 1 million of assets per month (₹1,000 per crore; 1 basis point) |
| Enterprise | Priced on request | VPC deployment · multiple entities · custom integrations · procurement and security review · dedicated engineering support · Price on request |
The facts
Each one read from Lokta's own pages, with the date it was checked.
What it does
- Adoption model
- The company uses founder-led adoption with a small cohort of lenders and starts with a drift audit before anything moves.checked 30 Sep 2026
- AI governance
- AI agents propose actions while deterministic policy checks and required human approvals control changes to the loan book, with proposals and outcomes recorded.checked 15 Oct 2026
- AI models
- The integration page lists OpenAI, Anthropic, Google Gemini, Meta Llama, Mistral, Cohere and self-hosted open models as supported model choices.checked 30 Sep 2026
- API
- Lokta documents a REST API with 314 endpoints grouped into 35 sections.checked 15 Oct 2026
- API authentication
- Requests use HTTP Basic credentials and a Tenant-Identifier header, with idempotency and pagination conventions documented.checked 15 Oct 2026
- API documentation
- API pages provide schemas, parameters, runnable samples in five languages, Markdown versions, Postman collection, OpenAPI specification, conventions and error guidance.checked 15 Oct 2026
- Collateral
- Collateral management tracks assets, valuations and documents through the life of a loan.checked 15 Oct 2026
- Collections
- Collections tools manage overdue accounts, promises to pay, follow-up queues and recovery records.checked 15 Oct 2026
- Crunchbase founders
- Crunchbase lists Ashok Auty and Nayan Ambali as founders and describes the company as active, private and for-profit.checked 15 Oct 2026
- Crunchbase legal entity
- Crunchbase identifies the legal name as Lokta Tech Private Limited and lists Bangalore, Karnataka, India as headquarters.checked 15 Oct 2026
- Data residency
- Tenants can pin deployments to a specific region, with separate deployments for each residency boundary.checked 30 Sep 2026
- Deployment
- Lokta describes AWS, Azure, Google Cloud, on-premises and customer-VPC deployments, with Docker images available for private deployment.checked 15 Oct 2026
- Google Play identity
- The Google Play listing named Lokta is published by ITServiceNepal (Code Durbar), describes retail accounting and inventory features, and shows 500+ downloads without a displayed numeric rating.checked 15 Oct 2026
- Integrations
- Ready integration examples include Digio, Cashfree, Gupshup, SMTP email, Tally and bureau reporting, while each provider is mapped and tested for the deployment.checked 15 Oct 2026
- Integration safety
- Every feed is risk-rated and proven safe in a controlled path before it can write to the live book.checked 30 Sep 2026
- Licence
- Lokta says it is a separate new codebase rather than an Apache Fineract fork or distribution, and no Lokta open-source licence is published on the reviewed pages.checked 15 Oct 2026
- Limit: integrations
- Integration logos do not guarantee prebuilt connectors; Lokta says providers require deployment-specific mapping, testing and acceptance.checked 15 Oct 2026
- Limit: origination
- Loan origination, underwriting, credit decisioning and origination-time pricing are outside the current product scope and described as roadmap work.checked 15 Oct 2026
- Limit: product scope
- The AI servicing page says leasing functionality and a voice bot are not included.checked 15 Oct 2026
- LinkedIn size
- LinkedIn reports a company size of 11–50 employees.checked 15 Oct 2026
- Loan accounting
- Interest, fee and repayment events generate accounting entries tied to individual loan transactions.checked 15 Oct 2026
Where it runs
- App-store identity
- The Apple App Store listing named Lokta is a separate finance app by IT Service Nepal PVT LTD, not Lokta Tech’s lending platform, and shows 5.0 out of 5 from 5 ratings.checked 15 Oct 2026
The company
- Company track record
- Lokta’s own biography attributes its team to Apache Fineract work associated with about $500 billion in cumulative principal, 65 million borrowers and 70 countries, while explicitly saying those totals are not Lokta’s own book.checked 15 Oct 2026
- LinkedIn company
- LinkedIn lists Lokta as a privately held software-development company founded in 2026 in Bangalore, Karnataka.checked 15 Oct 2026
The full review of Lokta
Lokta is a loan-servicing platform for lenders managing accounts after approval, rather than a system for starting or underwriting loans. It best suits banks, NBFCs, fintech lenders and lending service providers with operational needs across varied loan books. Its case rests on governed automation and a 24-month platform-fee waiver for eligible NBFCs, balanced against migration, integration and later usage costs.
Overview
Lokta covers servicing, monitoring, collections and recovery for personal, consumer-durable and BNPL, vehicle and EV, home, loan-against-property, business/MSME, and supply-chain or invoice-finance books. That breadth may suit lenders managing several products under one operation. It is not a fit for teams looking to bring origination, underwriting, credit decisions or origination-time pricing into the same platform.
Agents propose actions, but a deterministic core checks policy and approvals before any changes reach the ledger. Feeds are risk-rated and validated in a controlled path before they can write to the live book. Those controls are relevant where automated servicing touches sensitive records, although they do not replace the lender's own policies and oversight.
Key features
Integrations and deployment
Connections span NACH and UPI rails, payment aggregators, core banking and escrow, credit bureaus, co-lending partners, collection agencies and WhatsApp channels. Supported model choices include OpenAI, Anthropic, Google Gemini, Meta Llama, Mistral, Cohere and self-hosted open models, giving lenders a range of options for the agent layer. Lokta can run on AWS, Microsoft Azure, Google Cloud, on-premises or in a customer virtual private cloud.
Governance and security
Controls include Keycloak OIDC/OAuth2, role-based access, maker-checker workflows, structured audit trails, schema-per-tenant PostgreSQL isolation, field-level PII encryption, TLS and optional mTLS. Tenants can pin deployments to a region, with separate deployments for each residency boundary. This control set and the feed-validation process make Lokta more relevant to lenders with deployment and audit requirements than to organizations seeking a lightweight standalone loan tracker.
Payment scheduling, borrower portals, API access and both interest-calculation methods are supported. These are useful servicing building blocks, but they do not change the platform's post-approval boundary.
Pricing
The stated starting price is ₹1,000/mo. The programme pricing is more specific for qualifying NBFCs:
- Lokta Next 100: free, with a ₹0 platform fee for 24 months. Eligibility is limited to NBFCs with AUM up to ₹100 crore at enrolment and excludes pure-play microfinance NBFCs. Migration costs ₹1 lakh one-time plus applicable taxes; bank integration costs ₹50,000 plus applicable taxes.
- Lokta Next 100 after free term: ₹1 a month, billed at 1 bps per month on AUM (₹1,000 per crore), plus applicable taxes. This begins after 24 months or when average monthly AUM exceeds ₹100 crore for two consecutive months. AI usage is metered separately.
The waiver makes the programme worth considering for an eligible lender able to absorb the upfront migration and integration charges. It is not cost-free implementation, and the AUM-based charge plus separately metered AI usage matter when forecasting operating costs. Lenders outside the stated eligibility should not assume the programme terms apply.
Lokta says bureau reporting, email support and phone support are included in Next 100. The company begins adoption with a drift audit before anything moves and uses founder-led onboarding with a small cohort of lenders. That approach puts an initial assessment ahead of migration, but may be less suitable to buyers seeking a broad, self-serve rollout.
Platforms
Lokta supports API, Linux, self-hosted and web deployments. Its cloud, on-premises and virtual-private-cloud options give lenders choices for where the system runs, while regional deployment pinning addresses residency boundaries.
Who it's for
Lokta is best suited to banks, NBFCs, fintech lenders and lending service providers that need servicing and recovery operations across one or more supported loan types, and that value policy gates around agent-driven ledger changes. Eligible NBFCs within the Next 100 AUM threshold may find the free platform period compelling if the migration and integration charges fit their budget.
Look elsewhere if the priority is loan origination, underwriting or credit decisioning, or if a lender cannot accommodate the AUM-based post-waiver fee and separately metered AI usage.
Pros and cons
- Pros: Broad loan-book coverage supports lenders with varied portfolios rather than just one lending niche.
- Pros: Policy and approval checks gate proposed agent actions before ledger changes, while feeds are validated before live writes.
- Pros: Multiple deployment environments, regional pinning and explicit security controls suit organizations with infrastructure and data-residency constraints.
- Cons: Origination, underwriting, credit decisions and origination-time pricing are outside scope, so Lokta cannot cover the full lending lifecycle.
- Cons: Next 100 carries substantial one-time migration and bank-integration charges despite the platform-fee waiver.
- Cons: After the free term, charges scale with AUM and AI usage is separate, making ongoing cost depend on both portfolio size and usage.
Alternatives
For a broader category shortlist, see Loan Management Software.
- UnPay Loan Management System is worth considering if a freemium option with Android and iOS support is more important; its free Build plan includes 15 products in a sandbox, 480 API endpoints and community support.
- Frappe Lending suits buyers who want a self-hosted, GPL-3.0-licensed option, or a hosted Frappe Cloud Sites plan from $5 a month.
- FIS Data Integrity Manager is another paid, web-based option.
- The Mortgage Office is another paid option with API, macOS, web and Windows platforms.
- Margill Loan Manager may suit teams that prefer a loan-count- and user-based pricing model, with a free trial and SaaS or web monthly fees.
- Nortridge Loan System may suit lenders connecting an existing LOS for servicing and repo; its integration plan charges $10 per funded application, with a $300/month minimum and a variable setup fee.
- Bryt offers a Business version for up to 10 active loans and an Enterprise version for unlimited active loans, with add-on modules priced separately.
- Canopy is another paid, API- and web-based option.
Verdict
Choose Lokta if you are an eligible lender focused on post-approval servicing and want agent proposals governed before they affect the ledger. The Next 100 platform-fee waiver can help justify a closer look, but migration and bank integration are charged upfront and ongoing fees follow the programme's AUM and AI-usage terms. Choose another system if origination or credit decisions are central to your requirements.
Getting started
- Visit the Lokta website.
- Confirm eligibility for the Next 100 programme if seeking its zero platform fee.
- Plan for the ₹1 lakh one-time migration fee and any bank integration fee of ₹50,000, plus applicable taxes.
- Choose a deployment on AWS, Microsoft Azure, Google Cloud, on-premises, or a customer virtual private cloud.
- Start with the drift audit used in Lokta's founder-led adoption model.
- Connect required payment, banking, bureau, partner, agency, or WhatsApp feeds through a controlled path.
Limits worth knowing
The Next 100 zero platform fee applies for 24 months to eligible NBFCs with AUM up to ₹100 crore at enrolment, excluding pure-play microfinance NBFCs. Migration costs ₹1 lakh one-time and bank integration costs ₹50,000, plus applicable taxes; after 24 months or when average monthly AUM exceeds ₹100 crore for two consecutive months, the stated fee is 1 bps monthly on AUM, plus taxes, with AI usage metered separately.
Questions
Does Lokta have a free plan?
Its Next 100 plan is listed as free, with a zero platform fee for 24 months for eligible NBFCs. Eligibility limits apply, and migration and bank integration have separate charges.
What does Lokta cost after the free term?
The listed charge is 1 bps per month on AUM, equivalent to ₹1,000 per crore, plus applicable taxes. AI usage is metered separately.
Which loan types does Lokta support?
It supports personal, consumer durable and BNPL, vehicle and EV, home, loan-against-property, business/MSME, and supply-chain or invoice-finance books.
Where can Lokta be deployed?
Deployment options include AWS, Microsoft Azure, Google Cloud, on-premises, and a customer virtual private cloud.
Does Lokta handle loan origination or underwriting?
No. Loan origination, underwriting, credit decisioning, and origination-time pricing are currently out of scope.
Which AI model providers are supported?
The integration page lists OpenAI, Anthropic, Google Gemini, Meta Llama, Mistral, Cohere, and self-hosted open models.
Alternatives to Lokta
- 1
Frappe Lending
Free planOpen sourceWebAPISelf-hosted7.7From $5 a month - 2

Apache Fineract
Free planOpen sourceWebAPILinuxmacOS7.6Free plan - 3
UnPay Loan Management System
Free planAndroidiOSWebAPI6.7Free plan - 4
Shaw Systems Spectrum
WebAPI6.5$50,000 one-time - 5
AFSVision
AndroidiOSWebSelf-hosted6.3 - 6
Bryt
WebAPI6.3