Synctera
Synctera provides infrastructure for companies building and operating banking and embedded-finance products, and for sponsor banks managing those programs.
What Synctera is
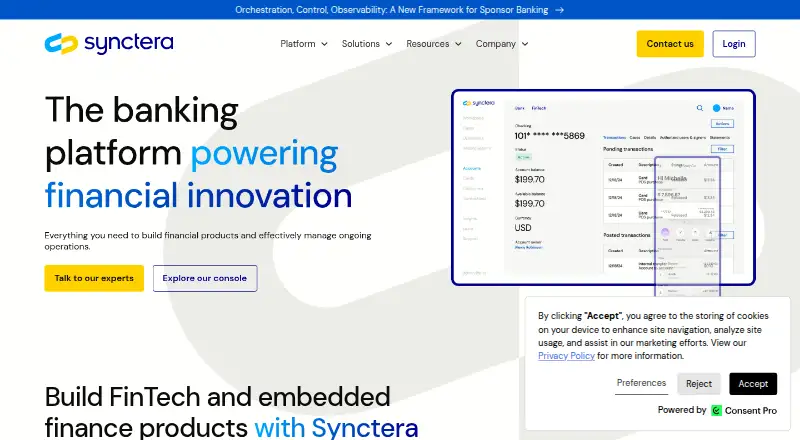
Synctera provides infrastructure for companies building and operating banking and embedded-finance products, and for sponsor banks managing those programs. Its APIs support core banking, card processing, and end-user onboarding for bank accounts, card programs, and money movement. Synctera Console handles account and end-user management, cases, insights, and reconciliation. Synctera Ledger stores end-user, account, and transaction data and supports automated interest calculations and statements. A white-label UX suite supplies pre-built components for onboarding, account and card management, and payments. Compliance capabilities include access to KYC, KYB, AML, and watchlist services, transaction monitoring, and workflow support. The partner ecosystem lists providers such as Plaid, Mastercard, Visa, Marqeta, Socure, and MX. Synctera’s Trust Center lists SOC 2 and PCI DSS 4.0.1 compliance resources and reports, while operational support covers disputes, KYC reviews, and fraud issues. Pricing is on request, and production API access depends on the Synctera products a FinTech subscribes to. Banking services come from partner banks; Synctera is not a bank.
Good
- APIs for core banking and card processing
- Ledger stores account and transaction data
- White-label onboarding and payment components
- KYC, KYB, AML, and watchlist access
- Console includes reconciliation and case management
Watch out
- Pricing is available only on request
- Production API access depends on subscribed products
- Synctera is not a bank
Who it suits
Synctera suits FinTech companies and embedded-finance businesses building accounts, cards, money movement, and related compliance workflows. It also serves sponsor banks managing embedded-finance programs.
Verdict
Synctera brings banking infrastructure, ledger functions, white-label experiences, and compliance tooling into an API and web platform. Its suitability depends on the products and sponsor-bank arrangements required by a financial business.
The facts
Each one read from Synctera's own pages, with the date it was checked.
What it does
- APIs
- Synctera APIs cover components including customer onboarding, payments, core banking, fraud monitoring, and card issuance and processing.checked 10 Oct 2026
- Banking products
- The platform supports bank accounts, card programs, and money movement experiences.checked 10 Oct 2026
- Banking services
- Synctera and its featured clients are financial technology companies, not a bank; banking services are provided by partner banks.checked 9 Oct 2026
- Compliance
- The platform provides access to KYC, KYB, AML, and watchlist tools, along with transaction monitoring and compliance workflow support.checked 9 Oct 2026
- Console and ledger
- Synctera Console provides account and end-user management, cases, insights, and reconciliation, while Synctera Ledger stores end-user, account, and transaction data.checked 9 Oct 2026
- Front-end
- Synctera offers a white-label UX suite with pre-built components for onboarding, account and card management, and payments.checked 9 Oct 2026
- Integrations
- The partner ecosystem lists providers including Plaid, Mastercard, Visa, Marqeta, Socure, and MX.checked 10 Oct 2026
- Intended customers
- Synctera says its platform serves companies building banking products and sponsor banks managing embedded finance programs.checked 9 Oct 2026
- Ledger
- Synctera Ledger stores end-user, account, and transaction data and supports features such as automated interest calculations and statements.checked 10 Oct 2026
- Operations
- Synctera Console provides account and end-user management, case management, insights, and reconciliation tools.checked 10 Oct 2026
- Partner integrations
- The partner ecosystem lists providers including Plaid, Marqeta, Mastercard, Visa, Socure, Finix, and Sardine.checked 9 Oct 2026
- Product
- Synctera provides infrastructure for companies to build and operate banking and embedded finance products.checked 9 Oct 2026
- Production access
- Production API access depends on the Synctera products to which a FinTech subscribes.checked 10 Oct 2026
- Purpose
- Synctera provides banking infrastructure for companies building and operating FinTech and embedded banking products.checked 10 Oct 2026
- Risk and compliance
- Synctera says its APIs connect customers to KYC, KYB, AML, and watchlist-checking services, with tools for monitoring and resolving compliance workflows.checked 10 Oct 2026
- Security and compliance
- Synctera’s Trust Center lists SOC 2 and PCI DSS 4.0.1 and provides access to security, privacy, compliance, and reliability materials.checked 10 Oct 2026
- Support
- Synctera describes operational compliance support for tasks including disputes, KYC reviews, and fraud issues.checked 10 Oct 2026
- White-label experience
- Synctera offers pre-built white-label components for onboarding, account and card management, and payments.checked 10 Oct 2026
- Who it serves
- Synctera serves FinTech and embedded-finance businesses and connects them with sponsor banks.checked 10 Oct 2026
The company
- Founded
- 2020checked 28 Sep 2026
- Headquarters
- Palo Alto, California, United Stateschecked 28 Sep 2026
Alternatives to Synctera
- 1
Stripe Treasury
Free planAndroidiOSWebAPI7.9$0.50 one-time - 2
Swan Cards
Free planAndroidiOSWebAPI7.9From €900 a month - 3

Modulr
AndroidiOSWebAPI7.2From £16.25 a month - 4
Mbanq Cloud
AndroidiOSWebAPI6.9 - 5
Railsr
Free planWebAPI6.8Free plan - 6
Rapyd
AndroidiOSWebAPI6.8From $99 a month