PayYantra
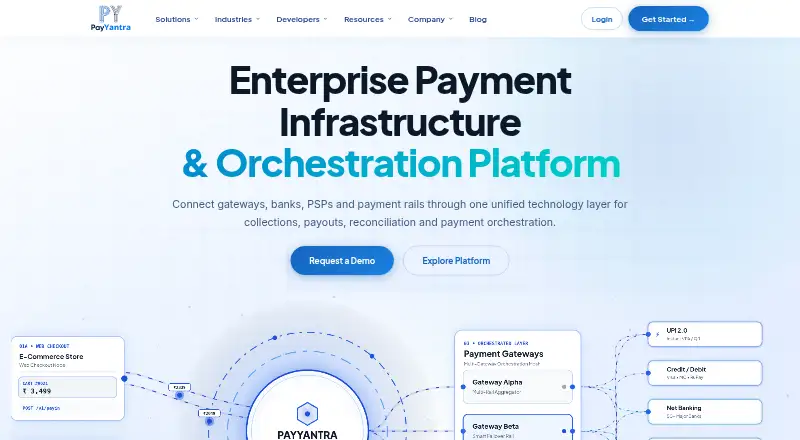
PayYantra is a payment infrastructure and orchestration platform for collections, payouts, routing, settlement, and reconciliation.
What PayYantra is
PayYantra is a payment infrastructure and orchestration platform for collections, payouts, routing, settlement, and reconciliation. Its unified payment API accepts UPI, cards, net banking, wallets, and buy now, pay later payments. The platform evaluates connected payment service providers using live performance information and routes transactions accordingly. Its payout service supports IMPS, NEFT, RTGS, and UPI. OmniVAN provides virtual accounts for collections, incoming-payment tracking, UTR capture, and automated reconciliation; eNACH supports mandates and scheduled collections. Developer materials describe REST APIs, webhooks, API keys, and a sandbox for simulating payment scenarios. Native SDKs are listed for iOS and Android, as well as React Native and Flutter. PayYantra says it serves enterprises, banks, NBFCs, fintechs, and regulated institutions. Pricing is on request. The company states that it is not a bank and that funds are held in nodal accounts with RBI-licensed scheduled commercial banks.
Good
- Accepts UPI, cards, net banking, wallets, and BNPL.
- Payouts support IMPS, NEFT, RTGS, and UPI.
- OmniVAN tracks incoming payments and UTRs.
- Developer materials include APIs, webhooks, and a sandbox.
- Native SDKs are listed for iOS and Android.
Watch out
- Pricing is available on request.
- PayYantra is not a bank.
- Funds are held in partner banks' nodal accounts.
Who it suits
PayYantra is aimed at enterprises, banks, NBFCs, fintechs, and regulated institutions that need payment collection, disbursement, or reconciliation services. Its APIs and SDKs may suit teams building payment flows into their systems.
Verdict
PayYantra brings collections, payouts, routing, and reconciliation into a payment infrastructure offering with developer tools. Organizations considering it should account for its stated non-bank status and contact the company for pricing and integration details.
The facts
Each one read from PayYantra's own pages, with the date it was checked.
What it does
- API security
- Its developer guide specifies Bearer token authentication over TLS 1.3 and support for idempotency keys on state-changing endpoints.checked 9 Oct 2026
- Audience
- The company describes its platform as serving enterprises, banks, NBFCs, and regulated fintechs.checked 9 Oct 2026
- Developer tools
- The developer materials describe REST APIs, webhooks, API keys, and an isolated sandbox for simulating payment scenarios.checked 9 Oct 2026
- Important limitation
- PayYantra states that it is not a bank and that funds are held in nodal accounts with RBI-licensed scheduled commercial banks.checked 9 Oct 2026
- Integrations
- OmniVAN lists SAP, Oracle, Tally, Zoho, and custom systems as ERP and system integrations.checked 9 Oct 2026
- Mobile SDKs
- The unified gateway page states that native SDKs are available for iOS and Android, as well as React Native and Flutter.checked 9 Oct 2026
- Payment collection
- Its payment collection service accepts UPI, cards, net banking, wallets, and buy now, pay later through one payment API.checked 9 Oct 2026
- Payment methods
- Its unified gateway supports UPI, cards, net banking, wallets, and BNPL through one API.checked 9 Oct 2026
- Payout rails
- Its developer documentation says payouts can be sent through IMPS, NEFT, RTGS, and UPI.checked 9 Oct 2026
- Payouts
- Its payout service supports IMPS, NEFT, RTGS, and UPI disbursements through one API.checked 9 Oct 2026
- Product
- PayYantra describes itself as a payment infrastructure and orchestration platform for collections, payouts, payment routing, and reconciliation.checked 9 Oct 2026
- Reconciliation
- PayYantra offers automated settlement reconciliation and ledger or MIS reporting across payment channels.checked 9 Oct 2026
- Recurring payments
- Its eNACH product supports mandate creation, scheduled collections, payment tracking, and reconciliation.checked 9 Oct 2026
- Routing
- The platform evaluates connected payment service providers and routes transactions using live performance information.checked 9 Oct 2026
- Security
- PayYantra's privacy policy names ISO/IEC 27001:2022, PCI-DSS v4.0.1, and SOC 2 among its security standards and says its information systems receive regular audits by CERT-In empanelled auditors.checked 9 Oct 2026
- Security controls
- The developer guide says API requests use Bearer token authentication over TLS 1.3 and webhook signatures use HMAC-SHA256.checked 9 Oct 2026
- Smart routing
- The platform evaluates connected PSP performance and routes transactions to optimize success rates.checked 9 Oct 2026
- Support
- The contact page lists [email protected] and offers contact for integration support and demo requests.checked 9 Oct 2026
- Virtual accounts
- OmniVAN provides virtual account collections, incoming payment tracking, UTR capture, and automated reconciliation.checked 9 Oct 2026
- What it does
- PayYantra describes itself as a payment infrastructure and orchestration platform for collections, payouts, payment routing, settlement, and reconciliation.checked 9 Oct 2026
- Who it serves
- PayYantra says it serves enterprises, banks, NBFCs, fintechs, and regulated institutions, with examples spanning education, healthcare, e-commerce, and government.checked 9 Oct 2026
The company
- Company
- The site identifies the company as PayYantra Innovations Pvt. Ltd. and says it was founded in Gurgaon.checked 9 Oct 2026
- Headquarters
- Gurgaon, Haryana, Indiachecked 28 Sep 2026
The full review of PayYantra
PayYantra is a cloud payment platform for organizations that need to manage collections, disbursements, routing, and reconciliation across several channels. It is best suited to enterprises and regulated financial businesses with developer resources; smaller buyers seeking a self-serve payment product should look elsewhere.
Overview
PayYantra combines payment collection, payouts, routing, settlement, and reconciliation through APIs. One gateway API handles UPI, cards, net banking, wallets, and buy now, pay later, while payouts can use IMPS, NEFT, RTGS, and UPI. The breadth is useful for organizations consolidating payment flows, but the platform is infrastructure rather than a bank: funds are held in nodal accounts at RBI-licensed scheduled commercial banks.
Live performance information from connected payment service providers informs transaction routing, which is intended to optimize success rates. That can help businesses managing multiple providers, though the value depends on having those connections in place and integrating the platform into existing operations.
Key features
Collections, payouts, and recurring payments
The unified collection API covers five payment categories, while the payout API supports four transfer rails. For businesses handling both incoming and outgoing payments, using one API for each side can reduce the number of separate channel integrations to maintain. eNACH adds mandate creation, scheduled collections, payment tracking, and reconciliation for recurring payments.
Virtual accounts and reconciliation
OmniVAN provides virtual account collections, incoming-payment tracking, UTR capture, and automated reconciliation. It also integrates with SAP, Oracle, Tally, Zoho, and custom systems. Automated settlement reconciliation and ledger or MIS reporting across channels give finance teams tools to bring payment activity together; this is a more relevant advantage for organizations with established reconciliation workflows than for businesses with simple payment needs.
Developer tools and security
REST APIs, webhooks, API keys, and an isolated sandbox for simulated payment scenarios support integration work before production use. Native SDKs are available for iOS and Android, alongside React Native and Flutter. The developer guide specifies Bearer-token authentication over TLS 1.3, HMAC-SHA256 webhook signatures, and idempotency keys for state-changing endpoints. PayYantra names ISO/IEC 27001:2022, PCI-DSS v4.0.1, and SOC 2 among its security standards and says its systems receive regular audits by CERT-In empanelled auditors.
Pricing
PayYantra is a paid product with custom pricing. There are no published plan tiers, prices, seat allowances, or usage quotas to compare, so organizations should request a quote and clarify the commercial terms for their expected transaction volumes and integrations before committing. Contact [email protected] for integration support or a demo request.
Platforms
PayYantra supports Android, iOS, web, and API access, with cloud deployment. Its native mobile SDKs and React Native and Flutter support give mobile teams several integration paths; businesses should confirm which option fits their application and implementation needs.
Who it's for
PayYantra targets enterprises, banks, NBFCs, fintechs, and regulated institutions, with use cases across education, healthcare, e-commerce, and government. It is a stronger fit for teams coordinating multiple payment methods, payout rails, or reconciliation workflows than for a small business looking for a straightforward checkout product. Because PayYantra is not a bank, buyers should also assess whether funds held in partner-bank nodal accounts suit their operating arrangements.
Pros and cons
Pros
- Broad payment coverage: A single collection API spans UPI, cards, net banking, wallets, and BNPL, while payouts cover IMPS, NEFT, RTGS, and UPI.
- Useful operational tooling: Virtual accounts, UTR capture, eNACH, and automated reconciliation address collection and finance workflows beyond basic payment acceptance.
- Integration options: REST APIs, webhooks, a sandbox, mobile SDKs, and ERP integrations support varied technical environments.
- Documented controls: TLS 1.3, HMAC-SHA256 webhook signatures, and idempotency keys provide concrete protections and safeguards for API operations.
Cons
- Custom pricing: Buyers cannot compare published tiers or costs and must contact the company to establish terms.
- Not a bank: Funds sit in nodal accounts with RBI-licensed scheduled commercial banks, a structural consideration for organizations assessing custody and payment operations.
- Enterprise orientation: Its range of APIs and payment workflows is better aligned with organizations that have integration capacity than with buyers seeking a simple, self-serve tool.
Alternatives
Consider CellPoint Digital or BR-DGE if you want to compare other paid platforms with Android, iOS, web, and API support. Gr4vy is another paid option with the same platform coverage; it has no free trial and uses custom pricing. Primer also supports those platforms and offers tailored pricing plans.
Temenos Wealth Front Office is a paid alternative for buyers considering API, self-hosted, and web platforms. ACI Automated Dispute Manager is a paid, web-based alternative without a free plan. VolPay Hub is a paid option for API, self-hosted, and web deployments. AccessPay supports API and web and prices its flat annual subscription according to estimated annual transaction volumes, users, and required data configurations and submission workflows.
For a broader comparison, browse Payment Hub Software.
Verdict
PayYantra is a strong candidate for enterprises and regulated financial businesses that need a single infrastructure layer for diverse collection methods, payouts, routing, and reconciliation. Its API and operational tooling are the main reasons to choose it. Look elsewhere if you need published pricing, a self-serve product, or a bank rather than a platform whose funds are held in partner-bank nodal accounts.
Getting started
- Open the PayYantra website
- Contact PayYantra for pricing or an integration demo
- Review the REST API, webhook, and API-key materials
- Use the isolated sandbox to simulate payment scenarios
- Choose native iOS or Android SDKs, or React Native or Flutter
- Connect supported ERP or custom systems through OmniVAN
Questions
What payment methods does PayYantra support?
Collections support UPI, cards, net banking, wallets, and buy now, pay later. Payouts support IMPS, NEFT, RTGS, and UPI.
Who is PayYantra designed for?
The company describes its audience as enterprises, banks, NBFCs, fintechs, and regulated institutions.
Does PayYantra provide developer tools?
Yes. Materials describe REST APIs, webhooks, API keys, idempotency keys, and an isolated sandbox.
Which SDK platforms are available?
Native SDKs are listed for iOS and Android, along with React Native and Flutter.
Is PayYantra a bank?
No. PayYantra states that it is not a bank and that funds are held in nodal accounts with RBI-licensed scheduled commercial banks.
How is PayYantra priced?
Pricing is available on request.
Alternatives to PayYantra
- 1
IXOPAY
AndroidiOSWebAPI7.6From $1,000 a month - 2
CellPoint Digital
AndroidiOSWebAPI6.5 - 3
BR-DGE
AndroidiOSWebAPI6.4 - 4

SAP CPQ
Web6.4From $24 a month - 5
PaymentHub
WebAPI6.2From $499 a month - 6
Spreedly
WebAPI6.2From $750 a month