Copulas.jl
The facts below are what the maker publishes about Copulas.jl, checked and dated. Our editors have not written about it yet.
The facts
Each one read from Copulas.jl's own pages, with the date it was checked.
What it does
- Additional interoperability
- An optional extension connects Copulas.jl with PartitionedDistributions.jl for marginal and conditional distribution operations.checked 12 Oct 2026
- Bayesian analysis
- Yeschecked 23 Sep 2026
- Compound distributions
- Its SklarDist type constructs multivariate compound distributions from a copula and marginal distributions using Sklar’s theorem.checked 12 Oct 2026
- Conditioning
- Copulas and SklarDist models can be conditioned on points or intervals; discrete margins are handled as latent uniform intervals.checked 11 Oct 2026
- Core features
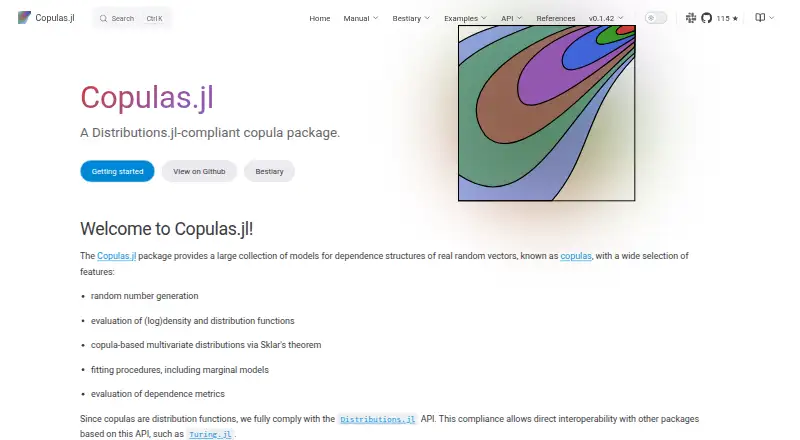
- The package supports random number generation, density and distribution function evaluation, fitting, copula based multivariate distributions, and dependence metrics.checked 12 Oct 2026
- Dependence analysis
- It provides dependence metrics, tail coefficients, and resampling-based hypothesis tests for dependence assumptions and goodness of fit.checked 11 Oct 2026
- Deployment
- desktopchecked 23 Sep 2026
- Diagnostics
- CopulaModel fitting supports diagnostics including covariance, confidence intervals, residuals, and information criteria.checked 11 Oct 2026
- Experimental status
- The project’s GitHub README describes the work as fairly experimental and advises using it with caution.checked 12 Oct 2026
- Fit limitation
- The documented Sklar fitting routes use sequential or rank-based methods and are not joint full maximum likelihood.checked 11 Oct 2026
- Fitting and selection
- The package offers fitting procedures and automatic family selection using explicit candidate sets and information criteria.checked 11 Oct 2026
- Installation
- The package is registered in Julia’s General registry and the site gives `] add Copulas` as the installation command.checked 12 Oct 2026
- Integration
- Copulas.jl follows the Distributions.jl API, supporting interoperability with packages based on that API such as Turing.jl.checked 11 Oct 2026
- Intended users
- The package is aimed at Julia users modeling dependence structures and multivariate distributions with copulas.checked 11 Oct 2026
- Julia ecosystem
- Copulas.jl follows the Distributions.jl API and the documentation describes interoperability with packages based on that API, including Turing.jl.checked 12 Oct 2026
- License
- The GitHub repository lists the package under the MIT license.checked 12 Oct 2026
- Model coverage
- The feature comparison marks extreme value copulas and Archimax copulas as bivariate only, and Archimedean chains as unavailable in Copulas.jl.checked 12 Oct 2026
- Numeric types
- The project describes its native Julia implementation as compatible with BigFloat, DoubleFloats, and MultiFloats.checked 12 Oct 2026
- Performance
- The project says efficiency and performance were not yet considered in its implementation priorities and that benchmarks would come later.checked 12 Oct 2026
- Plotting
- The documentation describes Plots.jl recipes for copula and SklarDist visualizations, including pairwise plots and bivariate density, log-density, or distribution contours.checked 12 Oct 2026
- Purpose
- Copulas.jl provides models for dependence structures of real random vectors, known as copulas.checked 12 Oct 2026
- Sampling and evaluation
- It supports random number generation and evaluation of log-density and distribution functions.checked 11 Oct 2026
Money
- Free plan
- Yeschecked 23 Sep 2026
The company
- Makers
- The package citation names Oskar Laverny and Santiago Jimenez as its authors.checked 12 Oct 2026